Products
SentimenTrader Trading Tools
‍
Backtest Engine
My Trading Toolkit
Correlation Analysis
Seasonality
Market Prediction
Indicators & Data API
‍
Proprietary Indicators & Charts
Market Data API
Strategies & Scanner
‍
50+ Trading Strategies
Smart Stock Scanner
Smart Option Scanner
Research Reports
‍
Research Solutions
Reports Library
Free Resources
Simple Backtest Calculator
Simple Seasonality Calculator
The Kelly Criterion Calculator
Sentiment Geo Map
Public Research Reports
Education
Sentiment Indicators
Technical Indicators
Pricing
Company
About
In the News
Testimonials
Client Success Stories
Contact
Log inLoginSign up
< BACK TO ALL REPORTS

TradingEdge Weekly for September 25, 2026 - Bitcoin Bounce Signals, Risk-Off Model Triggered, Smart Money vs Dumb Money, Semiconductor Rally, and Election Cycle Patterns
by Sentimentrader
2026-09-25
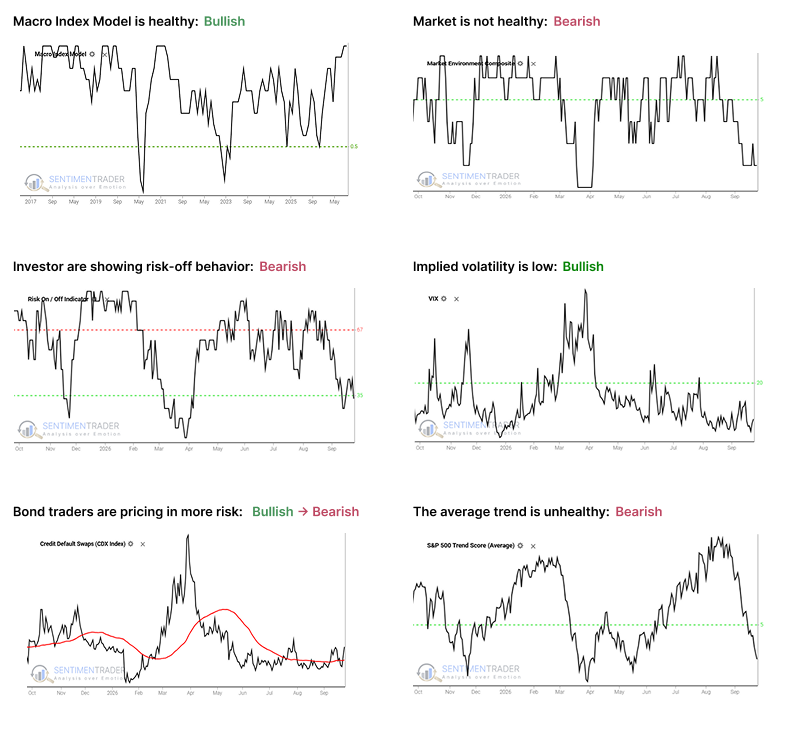
Despite short-term breadth deterioration and surging Treasury yields, the S&P 500 is about to enter its most historically bullish 11-month midterm election window, boasting a flawless win rate for 200-day holds since 1934.

Key points:

  • Bitcoin suffered 53% decline from October 2025 to June 2026, then bounced 38%; the 200-day MA of Bitcoin Optix crossed above 44.44 on August 21st, and the monthly Coppock Curve reached oversold; the Coppock Curve strategy showed 100% win rate with 53.8% average gain while in the market only 20% of the time.
  • The NYSE Percentage of New Lows and 200-Day Average Risk-Off Model triggered a risk-off signal; historically, the two-week win rate is only 45%, and over a 0- to 3-month horizon, the frequency of drawdowns exceeding 5% consistently outpaces that of gains greater than 5%, signaling a highly elevated probability of a near-term correction; SPX masks weakness by hovering within 4.5% of its 252-day high despite severe internal deterioration.
  • The Smart Money/Dumb Money Confidence Spread moved from a significantly negative reading to back above 0 on September 16th, flashing a green light for stocks in the short term; historical signals since 1998 showed an 86% win rate with exits when spread crosses back below 0 or after 84 trading days; when Dumb Money drops below 40% and Smart Money rises above 60%, stocks are often poised to rally over the next 1-3 months.
  • The Fear & Greed Model fell to 17 at its low, then moved back above 30 on September 18; median returns after the signal were mostly positive but showed no clear advantage against an ordinary trading day (one-year median about 10% vs 11%); within the 20-30 band, signals where sentiment was r

Sorry, you don't have access to this report

Upgrade your subscription plan to get access
Go to Dasboard
PRODUCTS
SentimenTrader
Trading Tools
Indicators & Data API
‍
Strategies & Scanner
‍
Research Reports
FREE
RESOUrCES
Simple Backtest
Calculator
Simple Seasonality
Calculator
The Kelly Criterion
Calculator
Sentiment Geo Map
‍
Public Research Reports
‍
Education
Sentiment Indicators
‍
Technical Indicators
‍
Pricing
Bundle pricing
‍
FAQ
‍
Announcements
‍
COMPANY
‍
About
‍
In the News
‍
Testimonials
‍
Client Success Stories
CONTACT
‍
General Inquiries
‍
Media Inquiries
‍
Financial Professionals Inquiries
‍
© 2026 Sundial Capital Research Inc. All rights reserved.
Setsail Marketing
TermsPrivacyAffiliate Program
Risk Disclosure: The information and tools provided are for research and analytical purposes only and are not intended as investment advice. Market analysis involves uncertainty, and outcomes may differ from expectations. Users should conduct their own due diligence and consider their individual circumstances before making any financial decisions. Past performance is not necessarily indicative of future results.

Hypothetical Performance Disclosure: Hypothetical performance results have many inherent limitations, some of which are described below. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown; in fact, there are frequently sharp differences between hypothetical performance results and the actual results subsequently achieved by any particular trading program. One of the limitations of hypothetical performance results is that they are generally prepared with the benefit of hindsight. In addition, hypothetical trading does not involve financial risk, and no hypothetical trading record can completely account for the impact of financial risk of actual trading. for example, the ability to withstand losses or to adhere to a particular trading program in spite of trading losses are material points which can also adversely affect actual trading results. There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all which can adversely affect trading results.

Testimonial Disclosure: Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.