Products
SentimenTrader Trading Tools
‍
Backtest Engine
My Trading Toolkit
Correlation Analysis
Seasonality
Market Prediction
Indicators & Data API
‍
Proprietary Indicators & Charts
Market Data API
Strategies & Scanner
‍
50+ Trading Strategies
Smart Stock Scanner
Smart Option Scanner
Research Reports
‍
Research Solutions
Reports Library
Free Resources
Simple Backtest Calculator
Simple Seasonality Calculator
The Kelly Criterion Calculator
Sentiment Geo Map
Public Research Reports
Education
Sentiment Indicators
Technical Indicators
Pricing
Company
About
In the News
Testimonials
Client Success Stories
Contact
Log inLoginSign up
< BACK TO ALL REPORTS

The S&P 500 liquidity premium indicator triggered a risk-on signal
Dean Christians
2024-09-27
A trading system that uses the S&P 500 Liquidity Premium indicator, a volume-derived sentiment measure, triggered a new risk-on signal. Comparable alerts in an uptrend produced outstanding returns and consistency for the S&P 500 over all time frames, especially in the subsequent month, rising 86% of the time.

Key points:

  • The S&P 500 Liquidity Premium indicator cycled from the upper end of its recent range to the lower half
  • Similar shifts in this volume-based sentiment indicator produced excellent returns for the S&P 500
  • The liquidity premium indicator can also be used to identify risk-off signals 

A sentiment gauge based on trading volume triggered a risk-on alert

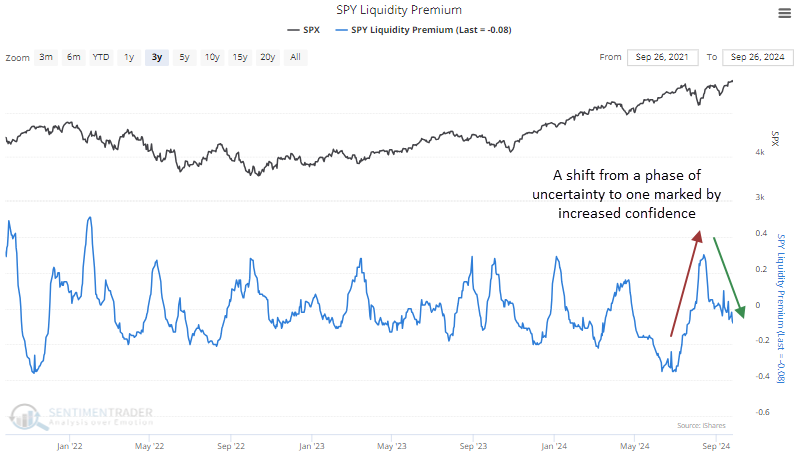
The S&P 500 Liquidity Premium indicator compares the volume of the S&P 500 ETF (SPY) to the volume of the underlying stocks comprising the S&P 500. When volume in the ETF increases relative to stocks, the indicator rises, indicating that investors are uncertain about the outlook for the market, a scenario typically associated with corrective phases. Eventually, confidence returns and volume increases in individual stocks compared to the ETF, causing the indicator to shift lower.

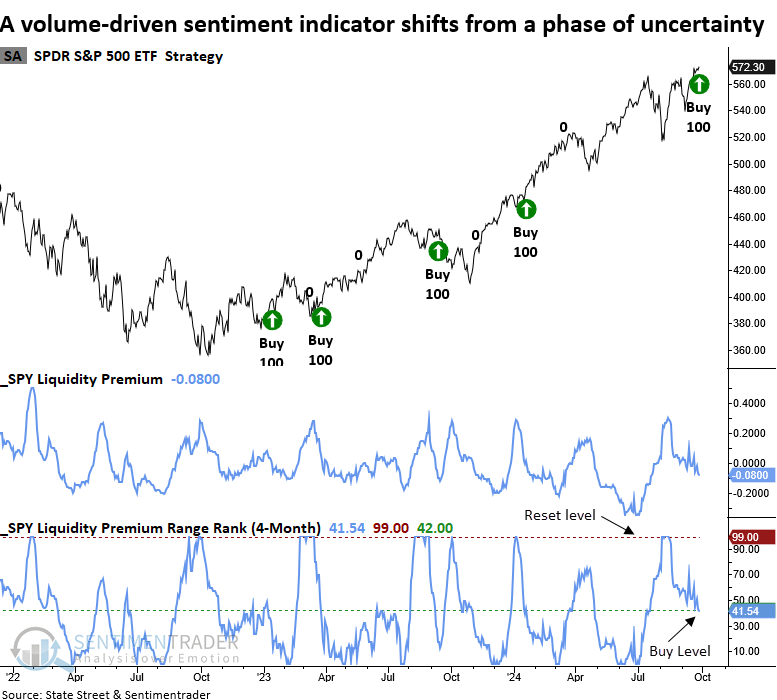
A trading model that utilizes the S&P 500 Liquidity Premium triggered a new risk-on signal, the first since January 2024. Following that alert, the S&P 500 gained 7.9% over two months.
The S&P 500 liquidity premium indicator triggered a risk-on signal

The system generates a buy signal whenever the 84-day range rank for the SPY Liquidity Premium indicator cycles from above 99% to under 42% and index momentum is positive. 

If you were curious, the QQQ Liquidity Premium indicator is trending toward a risk-on signal. 
The S&P 500 liquidity premium indicator triggered a risk-on signal

Similar volume-based sentiment shifts preceded a bullish outlook

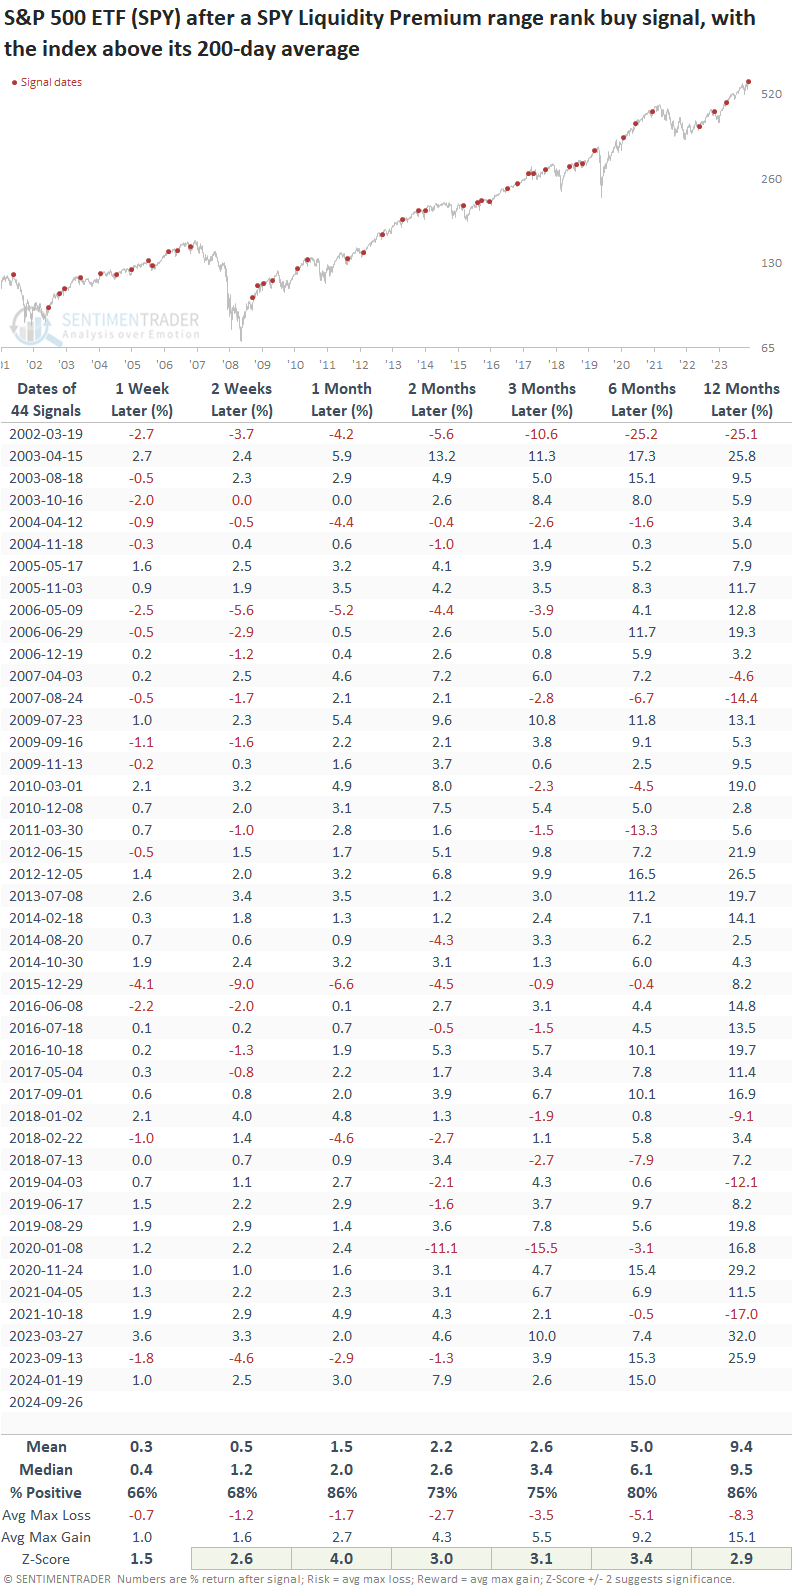
Whenever the SPY Liquidity Premium's 84-day range rank cycled from above 99% to less than 42%, with the index above its 200-day average and exhibiting positive momentum, the S&P 500 ETF (SPY) displayed excellent returns and consistency across all time frames. Furthermore, the signal exhibited significance relative to random returns in 6 out of 7 intervals.
The S&P 500 liquidity premium indicator triggered a risk-on signal

Can we use the Liquidity Premium indicator to signal risk-off?

After the July to August 2024 correction, I analyzed the liquidity premium indicator to determine its effectiveness as a risk-off signal. My findings revealed that it can serve as an early warning for a potential market correction. 

The methodology mirrors the risk-on signal but with reversed parameters. A risk-off signal is triggered when the Liquidity Premium indicator's 84-day range rank transitions from below 1% to above 50%, accompanied by negative index price momentum. 
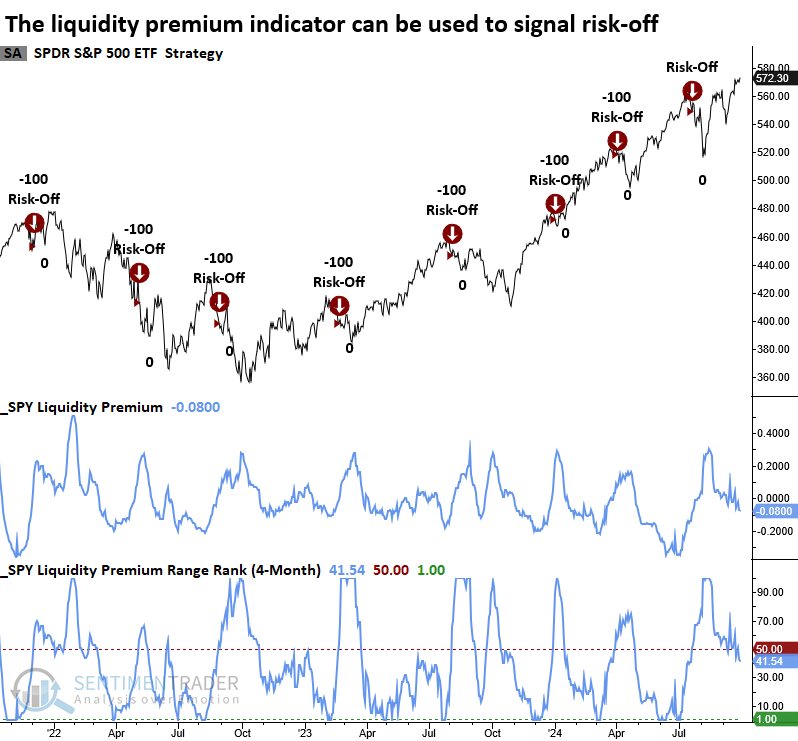
The S&P 500 liquidity premium indicator triggered a risk-on signal

Following liquidity premium risk-off signals, the S&P 500 showed a fairly strong tendency to decline in the near term, falling 67% of the time over two weeks. At some point in the next month, the world's most benchmarked index displayed a loss in 28 out of 39 cases.

The average maximum loss exceeded the average maximum gain from one week to three months. Furthermore, over longer horizons of six and twelve months, the average maximum gain marginally surpassed the average maximum loss. 
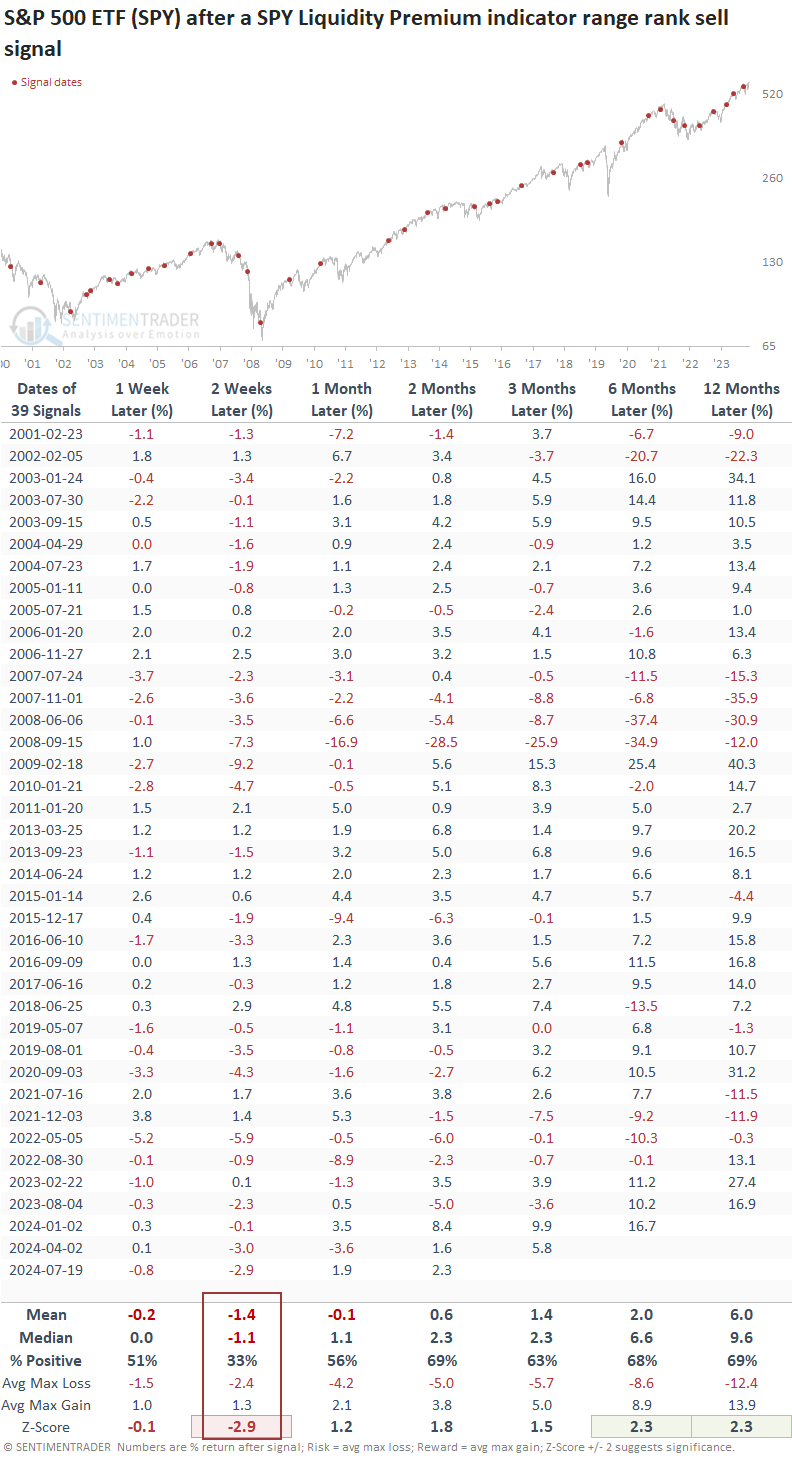
The S&P 500 liquidity premium indicator triggered a risk-on signal

The same system can be applied to the QQQ Liquidity Premium indicator. It triggers a risk-off signal when the 84-day range rank cycles from less than 1% to above 59% and index momentum is negative. Similar to the S&P 500 version, it's best used as a short-term signal. 

What the research tells us...

The S&P 500's Liquidity Premium indicator increased to an elevated level, indicating uncertainty or fear among investors. Subsequently, it reversed lower, triggering a risk on signal for stocks. Similar shifts in this volume-derived sentiment indicator produced outstanding returns and consistency for the S&P 500, especially when the index was in a long-term uptrend like now. The system for the liquidity premium indicator can be reversed to identify risk-off warnings. However, given the new risk-on signal, a warning will unlikely occur anytime soon. 

PRODUCTS
SentimenTrader
Trading Tools
Indicators & Data API
‍
Strategies & Scanner
‍
Research Reports
FREE
RESOUrCES
Simple Backtest
Calculator
Simple Seasonality
Calculator
The Kelly Criterion
Calculator
Sentiment Geo Map
‍
Public Research Reports
‍
Education
Sentiment Indicators
‍
Technical Indicators
‍
Pricing
Bundle pricing
‍
FAQ
‍
Announcements
‍
COMPANY
‍
About
‍
In the News
‍
Testimonials
‍
Client Success Stories
CONTACT
‍
General Inquiries
‍
Media Inquiries
‍
Financial Professionals Inquiries
‍
© 2026 Sundial Capital Research Inc. All rights reserved.
Setsail Marketing
TermsPrivacyAffiliate Program
Risk Disclosure: The information and tools provided are for research and analytical purposes only and are not intended as investment advice. Market analysis involves uncertainty, and outcomes may differ from expectations. Users should conduct their own due diligence and consider their individual circumstances before making any financial decisions. Past performance is not necessarily indicative of future results.

Hypothetical Performance Disclosure: Hypothetical performance results have many inherent limitations, some of which are described below. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown; in fact, there are frequently sharp differences between hypothetical performance results and the actual results subsequently achieved by any particular trading program. One of the limitations of hypothetical performance results is that they are generally prepared with the benefit of hindsight. In addition, hypothetical trading does not involve financial risk, and no hypothetical trading record can completely account for the impact of financial risk of actual trading. for example, the ability to withstand losses or to adhere to a particular trading program in spite of trading losses are material points which can also adversely affect actual trading results. There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all which can adversely affect trading results.

Testimonial Disclosure: Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.