
Semiconductor breadth is split inside and repairing overall
Key points:
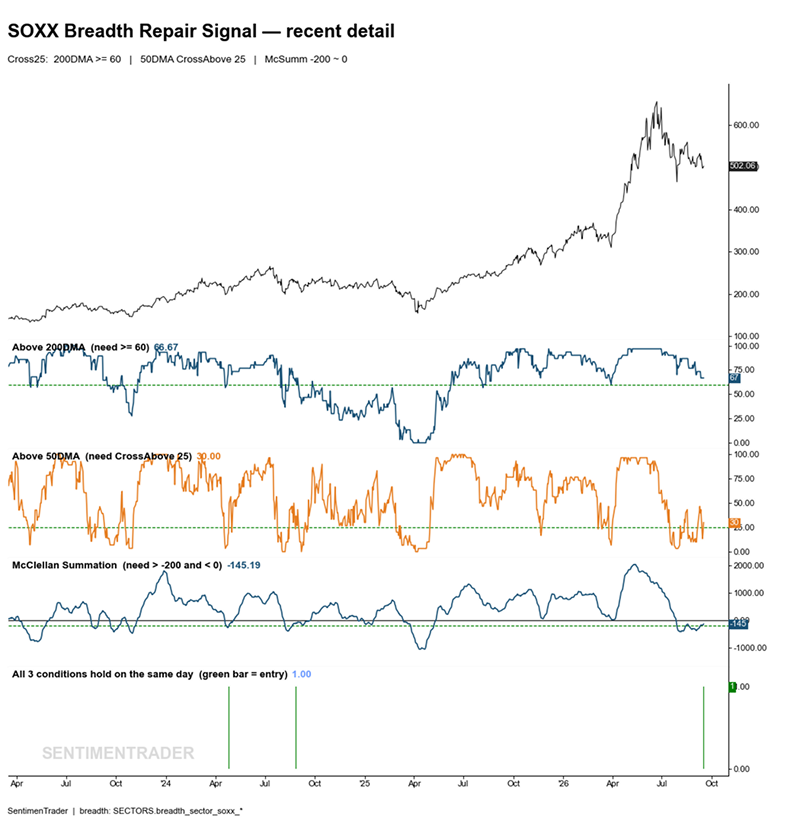
- Long-term breadth on SOXX is intact while mid-term breadth turns back up from a damaged level.
- The historical record for SOXX after this condition leans positive, but the sample is limited and the horizons disagree with each other.
- The internal difference is that the AI group is widely split while the cyclical group is uniformly weak.
- Industry volatility has already returned to normal, which looks like internal reordering.
Mid-term breadth is repairing from a damaged level
The Fed raised the target range for the federal funds rate by 25 basis points to 3.75% to 4.00% on Wednesday, putting the cost of funding back at the center of market discussion. Notably, this tightening did not arrive against a clearly recessionary economy. That combination is worth particular attention for semiconductors.
On one side, AI infrastructure and capital spending still support the strongest growth narrative in the group. On the other, a higher risk-free rate raises the cost of capital for duration assets. At the same time, autos, industrials, analog and the other more cyclical semiconductor businesses do not necessarily face the same demand environment as the AI compute chain.
If the whole group were taking nothing but a uniform rate shock, trends, breadth and volatility across its stocks should deteriorate together. Recent data does not look like that.