
NYSE Percentage of New Lows and 200-Day Average Risk-Off Model triggers a risk-off signal
Key points
- The NYSE Percentage of New Lows and 200-Day Average Risk-Off Model triggers a risk-off signal.
- Historically, this signal has been triggered either before or just after a significant correction or bear market peak.
- The maximum gain/loss table reveals that the frequency of drawdowns exceeding 5% consistently outpaces that of gains greater than 5% over a 0- to 3-month horizon, signaling a highly elevated probability of a near-term correction.
The NYSE percentage of new lows and 200-day average model
As I've stated numerous times in previous notes, new lows are a critical time series to monitor during bullish market trends. Currently, the number of NYSE stocks hitting 52-week new lows is steadily expanding.
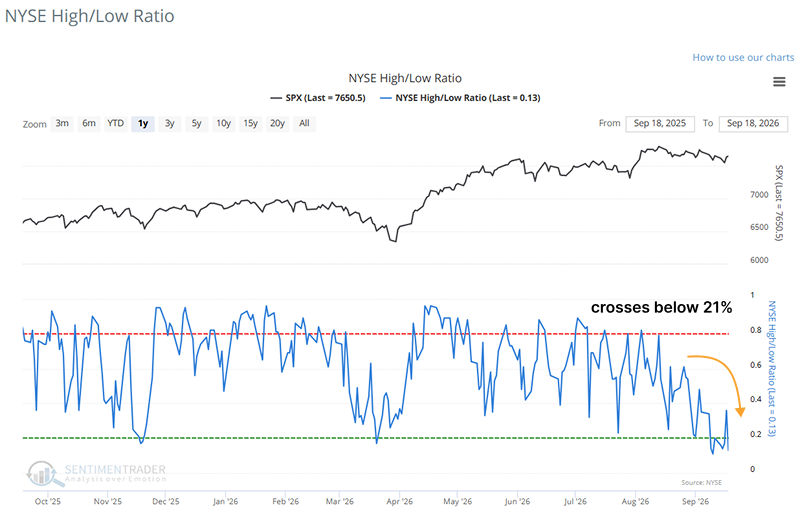
Simultaneously, the percentage of NYSE stocks trading above their 200-day moving average remains dangerously low. However, the true underlying risk lies in the glaring divergence: despite this severe internal deterioration, the broader S&P 500 index masks the weakness by continuing to hover within 4.5% of its 252-day high.